Periodic and Perpetual Inventory
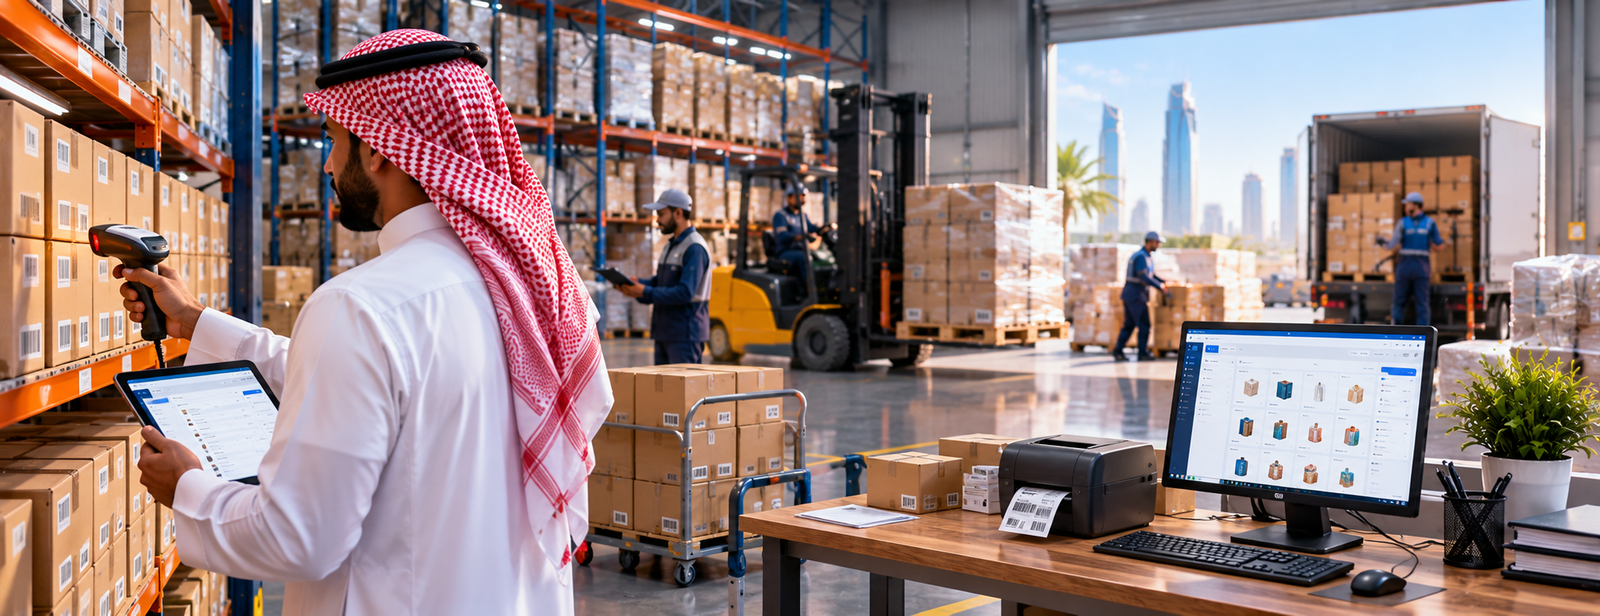
The difference between periodic and perpetual inventory is that periodic inventory determines the inventory balance and cost of goods sold at the end of a specified period after a physical inventory count, while a perpetual inventory system updates the inventory balance and cost of sales with every purchase, sale, or return recorded in the system.
Choosing between them is therefore not simply a matter of choosing a counting method, but of deciding how the business will account for inventory movements throughout the period.
If you manage a store with thousands of items, can you wait until the end of the month to find out how much stock remains? And if the system displays your balance in real time, does that mean you no longer need to physically count the inventory in your warehouse?
At AamalSoft, we recommend distinguishing between the inventory recording system and the physical counting process. You may use perpetual inventory for accounting purposes while still conducting periodic counts or partial counts to verify that the quantities in the system match reality.
You can learn more about organizing items and warehouses through the Warehouse Management guide to understand how to connect item movements with purchases, sales, and inventory counts.
What Is Periodic Inventory?
Periodic inventory is a system in which the inventory account and cost of goods sold are not continuously updated with each sale. Instead, ending inventory is determined through a physical count, and the cost of goods sold is then calculated at the end of the period.
The period may be:
- A month.
- A quarter.
- Half a year.
- A fiscal year.
Depending on the business's policies and needs.
Purchases are recorded during the period. At the end of the period, the inventory physically on hand is counted and valued to determine ending inventory.
How Do You Calculate the Cost of Goods Sold Under Periodic Inventory?
The method relies on the following formula:
Cost of Goods Sold = Beginning Inventory + Net Purchases - Ending Inventory
Example:
| Description | Value |
|---|---|
| Beginning Inventory | 100,000 SAR |
| Net Purchases | 300,000 SAR |
| Goods Available for Sale | 400,000 SAR |
| Ending Inventory | 120,000 SAR |
| Cost of Goods Sold | 280,000 SAR |
Calculation:
100,000 + 300,000 - 120,000 = 280,000 SAR
Therefore, the cost of the goods that left inventory during the period equals 280 thousand SAR.
What Is Perpetual Inventory?
Perpetual inventory is a system in which the inventory balance is continuously updated when purchases, sales, returns, transfers, and other transactions affecting inventory are recorded.
If you have 100 units of a product and sell 4 units, the recorded balance becomes:
100 - 4 = 96 units
And when you receive 20 new units:
96 + 20 = 116 units
This allows management to know the recorded balance at any time without waiting until the end of the period.
This model is particularly suitable for businesses that handle a large number of items and daily transactions.
The Integrated Accounting System connects sales and purchases with inventory and warehouses, so that recorded transactions are reflected in item balances and reports within the system.
What Is the Difference Between Periodic and Perpetual Inventory?
The difference can be summarized in the following table:
| Comparison | Periodic Inventory | Perpetual Inventory |
|---|---|---|
| Updating the Inventory Balance | At the End of the Period | With Every Transaction |
| Balance Visibility During the Period | Limited | Available Through the System |
| Cost of Goods Sold | Calculated at the End of the Period | Updated with Sales Transactions |
| Reliance on Physical Inventory Counts | Essential for Determining Ending Inventory | Used to Verify the Balance |
| Ease of Detecting Discrepancies | Lower During the Period | Faster |
| Suitability for Large Numbers of Items | Lower | Better |
| Need for an Inventory System | Lower | Important |
| Real-Time Data | Limited | Available |
However, this does not mean that perpetual inventory is better in every case; the choice depends on the size of the business, the number of transactions and products, and the business's ability to manage data.
Discover: Types of Inventory Counts in Warehouses
How Do Accounting Entries Differ Between Periodic and Perpetual Inventory?
One of the most important differences between the two systems is how inventory transactions are recorded.
When Purchasing Goods Under Periodic Inventory
Under the periodic system, the business typically uses a purchases account during the period.
Example of purchasing goods for cash worth 10,000 SAR:
| Account | Debit | Credit |
|---|---|---|
| Purchases | 10,000 | — |
| Cash or Bank | — | 10,000 |
Inventory and the cost of goods sold are then adjusted at the end of the period after ending inventory has been determined.
When Purchasing Goods Under Perpetual Inventory
The inventory account is updated directly:
| Account | Debit | Credit |
|---|---|---|
| Inventory | 10,000 | — |
| Cash or Supplier | — | 10,000 |
When Selling Under Perpetual Inventory
If a product is sold for 1,500 SAR and its cost is 900 SAR, two accounting transactions are recorded.
Sales entry:
| Account | Debit | Credit |
|---|---|---|
| Cash or Customer | 1,500 | — |
| Sales | — | 1,500 |
And the inventory cost entry:
| Account | Debit | Credit |
|---|---|---|
| Cost of Goods Sold | 900 | — |
| Inventory | — | 900 |
This is why a perpetual inventory system can display more up-to-date cost of sales and inventory balances.
Ready to Try the System?
Start your free trial or speak with our sales team for help choosing the right solution.
Does Perpetual Inventory Eliminate Physical Inventory Counts?
No.
This is a very important point.
Perpetual inventory tells you what should be in the warehouse based on the transactions that have been recorded.
A physical inventory count tells you what is actually there.
The system may indicate that you have:
500 units
But the physical count shows:
492 units
There is therefore a discrepancy of:
8 units
This may result from:
- An error in recording a sale.
- Damage.
- Theft or loss.
- An unrecorded return.
- An unrecorded receipt.
- An error during a transfer between warehouses.
- A counting error.
Many businesses therefore use a perpetual inventory system alongside periodic physical counts or ongoing partial counts to verify data accuracy.
What Is a Physical Inventory Count Under the Periodic System?
Under a periodic inventory system, the physical count is essential for determining the value of ending inventory.
The process usually involves:
- Stopping or organizing inventory movements during the count.
- Counting each item.
- Recording the actual quantity.
- Valuing inventory.
- Comparing the results with available records.
- Calculating ending inventory.
- Determining the cost of goods sold.
This is why the closing process may take longer in businesses with thousands of items.
What Are the Advantages of Periodic Inventory?
Its main advantages include:
- Simple implementation for small businesses.
- No need for an advanced inventory system.
- Lower operating costs in some cases.
- Suitable when the number of items and transactions is limited.
It may be sufficient for a small business that does not need to know the balance of each item in real time.
What Are the Disadvantages of Periodic Inventory?
The main disadvantages include:
- Difficulty knowing the exact balance during the period.
- Delayed detection of shortages or discrepancies.
- Difficulty tracking fast-moving items.
- Heavy reliance on counting at the end of the period.
- Limited data to support purchasing decisions.
- Greater difficulty when there are multiple branches or warehouses.
This is why businesses usually begin to feel the limitations of this system as transaction volumes increase.
What Are the Advantages of Perpetual Inventory?
Perpetual inventory offers a range of operational advantages, including:
- Knowing the recorded balance of each item.
- Tracking inventory movements.
- Continuously updating the cost of sales.
- Improving reorder decisions.
- Detecting discrepancies faster.
- Making it easier to manage multiple warehouses.
- Connecting sales with inventory.
- Generating more up-to-date reports.
It also becomes more effective when integrated with barcodes and point-of-sale systems.
You can consult the Point of Sale POS guide if daily sales are the main source of your inventory movements.
What Are the Disadvantages of Perpetual Inventory?
Despite its advantages, there are challenges to consider:
- It requires a reliable system.
- It depends on recording all transactions.
- A user error may directly affect the balance.
- It requires permission controls.
- It requires items and units to be defined correctly.
- It does not eliminate the need for physical counting.
- Implementation costs may be higher than those of a simple system.
If goods leave the warehouse without being recorded, the system will not automatically know about it, no matter how advanced it is.
A Practical Example Illustrating the Difference
Suppose a store started the month with:
100 units
Then purchased:
50 units
And sold:
80 units
The expected balance is therefore:
100 + 50 - 80 = 70 units
Under Perpetual Inventory
After all transactions are recorded, the system will show:
70 units
A physical count may then find 68 units, revealing an inventory discrepancy of two units.
Under Periodic Inventory
The business does not rely on continuous updates to its inventory accounting records, and the stock physically on hand is counted at the end of the period.
If the count shows:
68 units
This quantity is used to determine ending inventory and calculate the cost of goods sold.
Which Is Better: Periodic or Perpetual Inventory?
There is no single choice that suits all businesses.
Periodic Inventory May Suit:
- A very small business.
- A limited number of items.
- A low number of transactions.
- A business that does not need a real-time balance.
Perpetual Inventory Is More Suitable for:
- Supermarkets.
- Retail stores.
- Distribution companies.
- Pharmacies.
- Restaurants.
- Stores with multiple branches.
- Companies with multiple warehouses.
- Businesses with a large number of items.
As the number of products and transactions increases, so does the value of having up-to-date inventory data.
How Do You Know Your Company Needs to Switch to Perpetual Inventory?
You may need to change how you manage inventory if you face:
- Uncertainty about available quantities.
- Selling an item and then discovering it is out of stock.
- Large discrepancies at the end of an inventory count.
- Difficulty tracking item movements.
- Multiple warehouses.
- An increasing number of branches.
- Purchasing excessive quantities.
- Running out of important products.
- Reliance on Excel.
- Difficulty calculating the cost of goods sold.
If these problems recur, a perpetual system may be more suitable for the nature of the business.
How Does DigitalPro Help Manage Perpetual Inventory?
The Integrated Accounting System from AamalSoft connects:
Purchases → Inventory → Sales → Returns → Transfers → Accounts → Reports
When a purchase is recorded, quantities are added to inventory. When a sale is made, the recorded quantity decreases according to the transaction, allowing management to track item and warehouse balances through the system.
The system also supports the management of item units, barcodes, warehouses, and product movements, which are important functions for businesses that rely on perpetual inventory.
You can also use the Smart Reporting Portal to monitor sales and inventory indicators and reports linked to system data.
How Can You Reduce Inventory Discrepancies?
Whether you use periodic or perpetual inventory, you can reduce discrepancies by:
- Defining items consistently.
- Using barcodes.
- Recording all goods receipts.
- Recording sales as soon as they occur.
- Controlling returns.
- Documenting transfers between warehouses.
- Defining user permissions.
- Conducting regular physical inventory counts.
- Analyzing discrepancies instead of immediately adjusting them.
- Reviewing high-value or fast-moving items more frequently.
The goal is not just for the system to match the count, but to understand the cause of any discrepancy.
Common Mistakes When Implementing Periodic and Perpetual Inventory
Mistakes we recommend avoiding include:
- Believing that perpetual inventory eliminates physical counting.
- Using more than one code for the same item.
- Selling items without recording the transaction.
- Delaying the recording of purchases.
- Ignoring returns.
- Adjusting quantities manually without a reason.
- Failing to document transfers between warehouses.
- Relying on system quantities without physical verification.
- Conducting periodic inventory counts without analyzing discrepancies.
- Failing to connect point-of-sale systems with inventory.
Frequently Asked Questions About Periodic and Perpetual Inventory
What Is the Difference Between Periodic and Perpetual Inventory?
Periodic inventory determines the inventory balance and cost of goods sold at the end of a period after a physical count, while perpetual inventory updates the inventory balance with every recorded transaction.
Which Is Better, Periodic or Perpetual Inventory?
It depends on the size of the business. Periodic inventory may suit small businesses, while perpetual inventory is more suitable for stores and companies with many items and transactions or multiple warehouses and branches.
Does Perpetual Inventory Require Physical Inventory Counts?
Yes. Physical inventory counts are used to verify that the quantities in the system match the actual quantities in the warehouse.
How Do You Calculate the Cost of Goods Sold Under Periodic Inventory?
Using the formula:
Beginning Inventory + Net Purchases - Ending Inventory = Cost of Goods Sold.
Is Perpetual Inventory More Accurate?
It provides more up-to-date data, but its accuracy depends on correctly recording purchases, sales, returns, and transfers. Reviews and physical inventory counts therefore remain necessary.
Can Barcodes Be Used with Perpetual Inventory?
Yes. Barcodes help record item movements quickly and reduce some data entry errors during sales, receiving, and inventory counts.
In Conclusion
The main difference between periodic and perpetual inventory is when inventory data and the cost of sales are updated.
Under periodic inventory:
Record transactions → Conduct a physical count at the end of the period → Determine ending inventory → Calculate the cost of goods sold
Under perpetual inventory:
Purchase → Increase inventory → Sale → Decrease inventory and record the cost → Continuously monitor the balance
However, a perpetual system does not eliminate physical inventory counts; the software tells you what should be there, while counting tells you what is actually there.
This is why DigitalPro for Accounting and Point of Sale from AamalSoft connects purchases, sales, inventory, warehouses, and accounts to help businesses that need continuous monitoring of item movements.
You can also explore AamalSoft solutions, then request a trial and try recording a purchase, a sale, a return, and a physical inventory count, and review the effect of each transaction on the inventory balance.
Start Managing Your Business with Complete Flexibility
Try AamalSoft for free. Start issuing your ZATCA-compliant electronic invoices within minutes.
- Free trial without a credit card
- 24-hour technical support
- ZATCA compliant