The Difference Between Credit and Debit in Accounting: A Simple Explanation with Examples
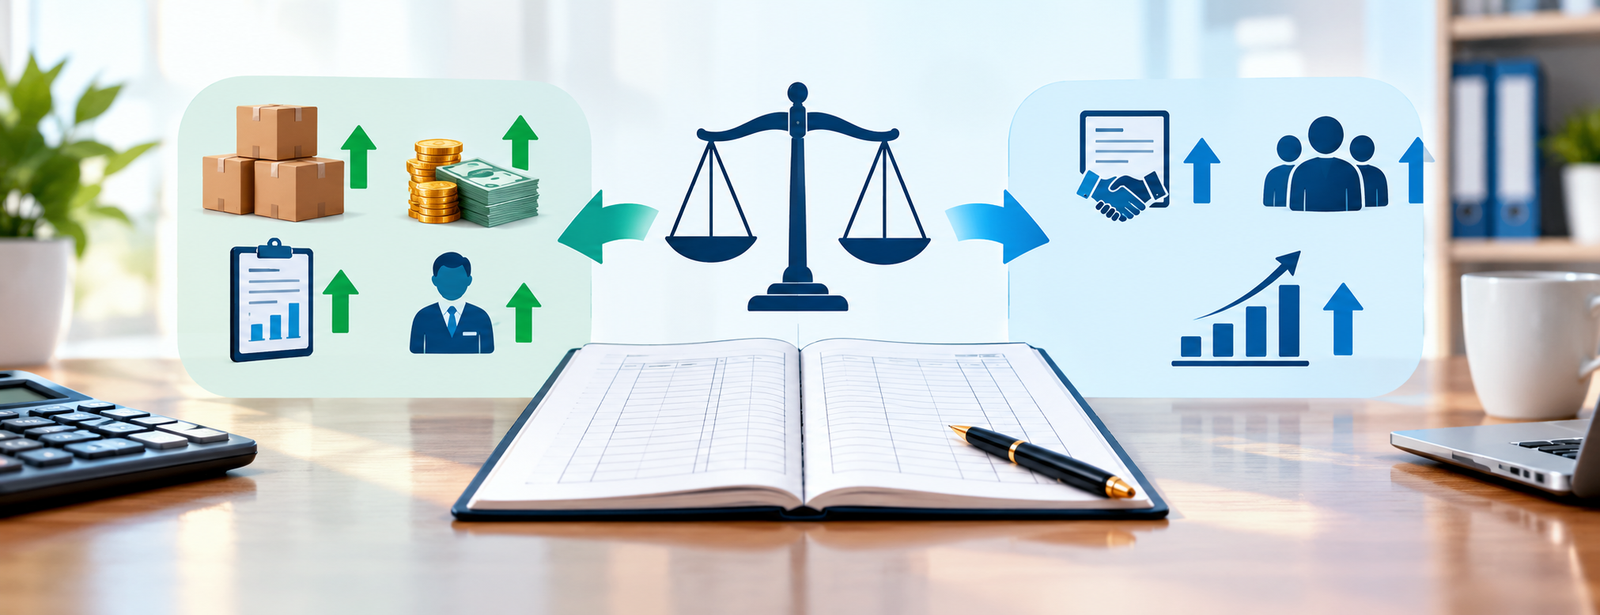
The difference between debit and credit in accounting is that debit represents the left side of an accounting entry, while credit represents the right side, and the effect of each depends on the type of account.
Assets and expenses increase on the debit side, while liabilities, equity, and revenue increase on the credit side.
Therefore, the word Debit does not always mean that someone owes a debt, just as the word Credit does not always mean that someone is owed money. For example, an increase in cash on hand is recorded on the debit side because it is an asset, while an increase in sales is recorded on the credit side because it is revenue.
The basic rule to remember is:
Total debits = Total credits in every balanced accounting entry.
At Aamal Raqmiyah we recommend understanding the nature of the account first rather than memorizing entries. When you know whether an account is an asset, liability, revenue, or expense, identifying the debit and credit sides becomes easier.
You can understand this relationship more fully through the guide to Elements of the Accounting System, which explains how transactions move from documents to entries, accounts, and reports.
What Do Debit and Credit Mean in Accounting?
Debit Debit is the left side of the entry, andCredit Credit is the right side.
However, determining which account belongs on each side depends on the type of account and the effect of the transaction on it.
| Account Type | When Increasing | When Decreasing |
|---|---|---|
| Assets | Debit | Credit |
| Expenses | Debit | Credit |
| Liabilities | Credit | Debit |
| Equity | Credit | Debit |
| Revenue | Credit | Debit |
This is the basic rule that helps you analyze most accounting transactions.
Ready to Try the System?
Start your free trial or speak with the sales team to help you choose the right solution.
How Do I Identify the Debit Account and the Credit Account?
Before recording any entry, use three steps:
- Identify the accounts affected by the transaction.
- Identify the type of each account.
- Determine whether the account increased or decreased.
Suppose the company purchased a piece of equipment for cash for 5,000 riyals.
The equipment is an asset that has increased, so it is debited. Cash is also an asset, but it has decreased, so it is credited.
Entry for Purchasing Equipment for Cash
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Equipment | 5,000 riyals | — | An asset increased |
| Cash on Hand | — | 5,000 riyals | An asset decreased |
| Total | 5,000 riyals | 5,000 riyals | The entry is balanced |
Thus, we can identify both sides of the entry through the account type and the direction of change rather than simply memorizing the entry.
Example of a Cash Sale
The company sold products for cash for 10,000 riyals, ignoring tax and cost of sales to simplify the example.
Cash increased, and it is an asset, so it is debited. Sales are revenue and have increased, so they are credited.
Cash Sale Entry
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Cash on Hand | 10,000 riyals | — | An asset increased |
| Sales | — | 10,000 riyals | Revenue increased |
| Total | 10,000 riyals | 10,000 riyals | The entry is balanced |
This example explains why the word “debit” does not mean that cash on hand owes a debt; rather, it indicates the accounting side on which the increase is recorded.
Why Does a Customer Have a Debit Balance?
When a company sells to a customer on credit, an amount becomes due from the customer, so the customer's account is usually recorded on the debit side.
Suppose the company issued a credit sales invoice for 20,000 riyals.
Entry for a Credit Sale to a Customer
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Customer | 20,000 riyals | — | Increase in accounts receivable |
| Sales | — | 20,000 riyals | Increase in revenue |
| Total | 20,000 riyals | 20,000 riyals | The entry is balanced |
If the customer subsequently pays 7,000 riyals:
Entry for Receiving a Payment from a Customer
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Bank or Cash on Hand | 7,000 riyals | — | Increase in cash |
| Customer | — | 7,000 riyals | Decrease in the amount due from the customer |
| Total | 7,000 riyals | 7,000 riyals | The entry is balanced |
The customer's remaining balance becomes:
20,000 - 7,000 = 13,000 riyals debit
This is why the accounting system needs to link sales invoices and collections directly to the customer's account.
An integrated accounting system from Aamal Raqmiyah provides customer, sales, and collections management within an interconnected accounting cycle.
Why Does a Supplier Have a Credit Balance?
When a company purchases from a supplier on credit, it incurs a liability to that supplier, so the supplier's account usually shows a credit balance.
Suppose the company purchased goods worth 30,000 riyals on account.
Entry for a Credit Purchase from a Supplier
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Purchases or Inventory | 30,000 riyals | — | Increase in purchases or the asset |
| Supplier | — | 30,000 riyals | Increase in the liability to the supplier |
| Total | 30,000 riyals | 30,000 riyals | The entry is balanced |
If the company pays the supplier 10,000 riyals:
Entry for Payment to a Supplier
| Account | Debit | Credit | Reason for Treatment |
|---|---|---|---|
| Supplier | 10,000 riyals | — | Decrease in the liability |
| Bank or Cash on Hand | — | 10,000 riyals | Decrease in cash |
| Total | 10,000 riyals | 10,000 riyals | The entry is balanced |
The remaining amount owed to the supplier is:
30,000 - 10,000 = 20,000 riyals credit
You can review the guide to Sales and Purchases Accounting to understand the effect of sales and purchases on customer and supplier accounts.
The Difference Between a Customer Debit Balance and a Supplier Credit Balance
| Transaction | Affected Account | Effect |
|---|---|---|
| Credit sale to a customer | Customer | Debit |
| Receiving a payment from a customer | Customer | Credit, reducing the balance |
| Credit purchase from a supplier | Supplier | Credit |
| Payment to a supplier | Supplier | Debit, reducing the balance |
In brief:
Customer debit balance = An amount owed to the company.
Supplier credit balance = An amount owed by the company.
However, there are cases where a customer may have a credit balance or a supplier may have a debit balance.
Can a Customer Have a Credit Balance?
Yes.
This may happen when:
- The customer pays in advance.
- The customer pays more than the outstanding balance.
- A return is recorded after the invoice has been paid.
- An adjustment results in a balance in the customer's favor.
For example, if the customer pays 5,000 riyals in advance before any invoice is issued:
Entry for an Advance Payment from a Customer
| Account | Debit | Credit |
|---|---|---|
| Bank or Cash on Hand | 5,000 riyals | — |
| Customer Account | — | 5,000 riyals |
| Total | 5,000 riyals | 5,000 riyals |
The customer's account may therefore show a credit balance until the amount is offset against a later invoice.
Can a Supplier Have a Debit Balance?
Yes.
If a company pays a supplier in advance before receiving the goods or recording the purchase invoice, the supplier's account may show a debit balance.
Example of an Advance Payment to a Supplier
| Account | Debit | Credit |
|---|---|---|
| Supplier | 10,000 riyals | — |
| Bank or Cash on Hand | — | 10,000 riyals |
| Total | 10,000 riyals | 10,000 riyals |
Therefore, the accuracy of a balance should not be judged by the word “debit” or “credit” alone; the transactions that produced the balance must be reviewed.
How Do Debits and Credits Appear on an Account Statement?
An account statement usually contains:
- Date.
- Document number.
- Description.
- Debit.
- Credit.
- Balance.
Example of a customer account:
| Transaction | Debit | Credit | Debit Balance |
|---|---|---|---|
| Sales invoice | 10,000 | — | 10,000 |
| Collection | — | 4,000 | 6,000 |
| New invoice | 5,000 | — | 11,000 |
| Collection | — | 3,000 | 8,000 |
The final balance is therefore:
8,000 riyals debit
This is why understanding both sides of an entry is important when reviewing customer and supplier account statements and reconciling balances.
The Difference Between Debits and Credits in Assets and Liabilities
Assets
These include:
- Cash on hand.
- Bank.
- Customers.
- Inventory.
- Equipment.
| Change in the Asset | Treatment |
|---|---|
| Increase in the asset | Debit |
| Decrease in the asset | Credit |
Liabilities
These include:
- Suppliers.
- Loans.
- Accrued liabilities.
| Change in the Liability | Treatment |
|---|---|
| Increase in the liability | Credit |