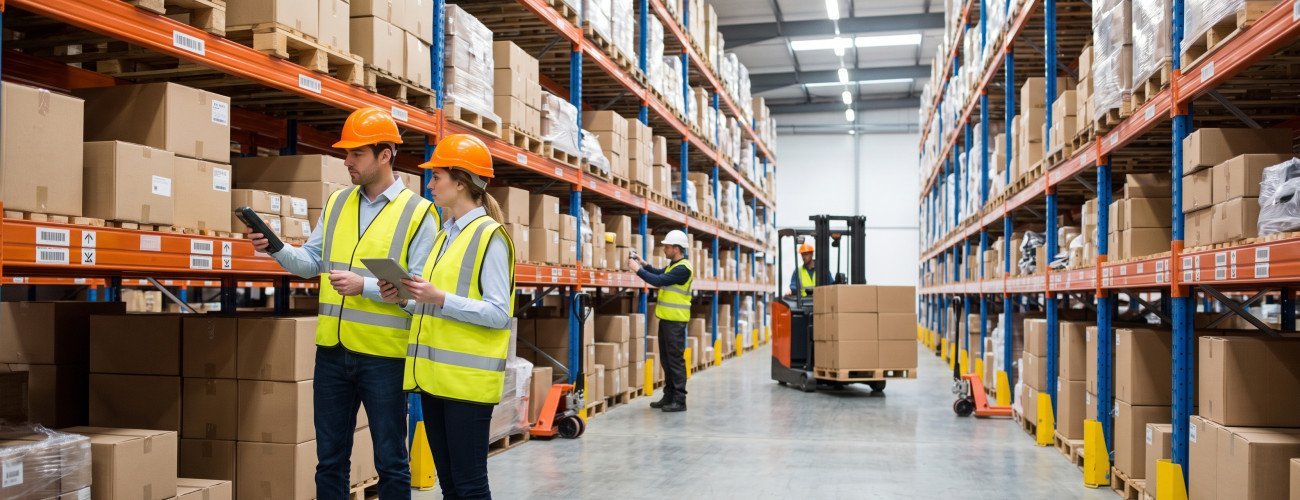
Types of Inventory Counting in Warehouses
Knowing the types of inventory counting in warehouses is one of the fundamentals of financial and warehouse management, because having a product balance in the system does not necessarily mean that the same quantity actually exists on the shelves.
Differences may occur due to an error in receiving or issuing, an unrecorded return, damage, a transfer between warehouses, or incorrect quantity entry. This is where inventory counting comes in to compare the book balance or the balance recorded in the system with the actual balance in the warehouse.
In brief, the main types of inventory counting are:
- Comprehensive inventory counting.
- Periodic inventory counting.
- Continuous or cycle counting.
- Partial or selective inventory counting.
- Surprise inventory counting.
- Exceptional inventory counting.
There is no single type that is best for all businesses; the choice depends on inventory size, the number and value of items, their movement rate, the number of warehouses, and the nature of the activity.
To understand inventory counting within the complete warehouse cycle, you can review the guide Warehouse Management, Inventory Organization, and Inventory Counting، which explains the receiving, storage, issuing, transfer, returns, inventory counting, and adjustment cycle.
What Is Inventory Counting in Warehouses?
Inventory counting in warehouses is the process of determining the actual quantities of items in the warehouse and comparing them with the balances recorded in the system, then identifying and addressing the causes of differences before carrying out the necessary inventory and accounting adjustments.
Example:
Balance recorded in the system = 500 units
Actual quantity = 487 units
Inventory difference:
487 - 500 = -13 وحدة
This means there is a shortage of 13 units, and its cause must be identified before adjusting the balance.
The difference may be due to:
- Unrecorded sales or issues.
- A return that was not added.
- Damage or wastage.
- Theft or loss.
- An error in receiving.
- An error in counting.
- An incomplete transfer between two warehouses.
- Incorrect unit of measure entry.
- An error in recording the quantity in the system.
Therefore, inventory counting is not merely counting products; it is a control process for verifying the quality of inventory data.
What are the types of inventory counting in warehouses?
Inventory counting can be classified according to the scope of items, timing, and reason for conducting it.
| Inventory Counting Type | Method of Execution | Suitable For |
|---|---|---|
| Comprehensive inventory counting | Counting all items | Annual closing and general review |
| Periodic inventory counting | At specified times | Most companies and warehouses |
| Continuous or cycle counting | Continuously counting groups of items | Large warehouses |
| Partial inventory counting | Counting specific items | Important or high-risk products |
| Surprise inventory counting | Without prior notice | Control and detection of differences |
| Exceptional inventory counting | Upon a specific event | Change of responsible person or occurrence of a problem |
First: Comprehensive Inventory Counting
Comprehensive inventory counting is the process of determining all items present in all specified locations within the warehouse at a specific time.
It is usually performed when:
- End of the fiscal year.
- Closing an important accounting period.
- Changing the accounting system.
- Reorganizing warehouses.
- Fully valuing the inventory.
- Auditing processes.
Advantages of Comprehensive Inventory Counting
- Provides a complete picture of the actual balance.
- Reveals differences across a large number of items.
- Helps review inventory value.
- Provides a good basis for adjustments.
Disadvantages
It may require:
- A long time.
- A large number of employees.
- Advance organization.
- Stopping or reducing some movements during counting.
- Careful review of counted items.
Therefore, performing it frequently may be impractical for businesses with thousands of items.
Second: Periodic Inventory Counting
Periodic inventory counting is conducting inventory counting at predetermined intervals, such as the end of each month, quarter, half-year, or year.
For example:
- Monthly inventory counting.
- Quarterly inventory counting.
- Semi-annual inventory counting.
- Annual inventory counting.
The business determines the frequency according to the size of the activity and risks.
When Is Periodic Inventory Counting Suitable?
It is suitable when:
- The number of items is moderate.
- The business does not need daily counting.
- Inventory movement is manageable.
- There are fixed review dates.
explains أعمال رقمية in its warehouse management guide that periodic inventory counting can be performed monthly, quarterly, or annually according to the business's needs.
Third: Continuous or Cycle Counting
Continuous or cycle counting relies on repeatedly counting specific groups of items throughout the year instead of waiting to count the entire warehouse at one time.
For example, inventory can be divided into groups:
- Group A: Weekly.
- Group B: Monthly.
- Group C: Quarterly.
Higher-value or faster-moving items are counted more frequently.
Why Do Companies Use Continuous Inventory Counting?
Because it helps to:
- Detect errors early.
- Reduce the accumulation of inventory differences.
- Avoid waiting until the end of the year.
- Focus on the most important products.
- Improve the accuracy of system data.
- Reduce the need to stop operations for a long period.
It is particularly suitable for large stores, distribution companies, and warehouses containing a huge number of items.
Does Continuous Inventory Counting Mean There Is No Need for Physical Counting?
No.
There is a common confusion between continuously recording inventory movement and physical inventory counting.
The system can update the balance with every purchase, sale, issue, or transfer, but physical inventory counting remains necessary to verify that the recorded balance matches what actually exists.
DigitalPro provides the ability to monitor inventory, product movement, suppliers, and warehouses within the sales and accounting system, but balance quality also remains linked to the accuracy of recording transactions and inventory counting.
Fourth: Partial or Selective Inventory Counting
Partial inventory counting is counting a specific group of items without counting the entire inventory.
Products can be selected based on:
- High value.
- Movement speed.
- Frequent previous differences.
- Likelihood of damage or loss.
- Approaching expiration.
- Importance of the item to the business.
Example
A store has 5,000 items, but management noticed that 150 items represent a large portion of the inventory value.
Instead of counting 5,000 items weekly, the 150 items can be counted more frequently.
This method is also known in some environments as selective inventory counting.
The Warehouse Management guide from Aamal Digital explains the ability to prioritize high-value or fast-moving items, or items with recurring differences, in selective inventory counting.
Fifth: Surprise Inventory Counting
Surprise inventory counting is conducting a counting process without giving the employees responsible for inventory advance notice of the date.
It is usually used for control and verification purposes.
For example, management may decide to conduct a surprise count of:
- Cash and inventory.
- A high-value item.
- A specific warehouse.
- A branch where recurring differences have appeared.
- Fast-moving items.
What Is the Purpose of Surprise Inventory Counting?
It helps with:
- Detect unusual differences.
- Assess compliance with warehouse procedures.
- Limit manipulation.
- Verify the accuracy of recording issues and receipts.
- Test the quality of internal controls.
It is not recommended as a substitute for an organized inventory counting plan; rather, it is a supplementary control tool.
Sixth: Exceptional Inventory Counting
Exceptional inventory counting is conducted when a specific event occurs that requires knowing the actual balance immediately.
Examples include:
- Changing the warehouse custodian.
- A new person taking responsibility for the warehouse.
- Discovering a large difference.
- A theft occurring.
- Fire or damage.
- Relocating the warehouse.
- Merging two branches.
- Changing the inventory management system.
- Liquidating the business.
The goal here is not to follow a periodic schedule, but to determine responsibility and establish the actual balance on a specific date.
What is the difference between periodic and continuous inventory counting?
This is one of the most common questions when discussing types of inventory counting in warehouses.
| Comparison | Periodic inventory counting | Continuous inventory counting |
|---|---|---|
| Counting timing | At specified times | Throughout the year |
| Items | Large number or the entire warehouse | Specific groups |
| Error detection | At the time of counting | Faster |
| Operational disruption | May be greater | Usually lower |
| عدد Items | Suitable for less complex inventory | Suitable for large inventory |
| Monitoring | At intervals | Continuous |
| Planning | Clear counting date | Year-round cycle plan |
In practice, a business can use both methods together.
It may conduct a comprehensive periodic count once a year, along with continuous counting of important items throughout the year.
Difference Between Comprehensive and Partial Inventory Counting
Comprehensive inventory counting covers all items, while partial inventory counting focuses on a specific group.
Example:
A warehouse contains 10,000 items.
- Counting 10,000 items = comprehensive inventory counting.
- Counting only 500 items = partial inventory counting.
Partial inventory counting is faster, but by itself it does not provide a complete picture of all warehouse balances.
Which Type of Inventory Counting Suits Your Business?
The choice of method depends on the nature of the business:
| Business Activity | Usually Suitable Method |
|---|---|
| Small store | Periodic + surprise when needed |
| Supermarket | Continuous + periodic |
| Distribution company | Continuous + selective + comprehensive |
| Large warehouse | Cycle Counting + شامل |
| Restaurant | Continuous for important materials + periodic |
| Online store | Continuous + selective |
| Factory | Continuous for important materials + comprehensive periodic |
| High-value items | Selective and surprise counting more frequently |
The table should not be applied in only one way; a business may need to combine several types according to the level of risk.
Read also: A simplified guide to the warehouse document cycle
How Is Inventory Counting Performed in Warehouses Step by Step?
Good inventory counting starts before the physical count.
1. Define the Inventory Counting Scope
Define:
- The warehouse.
- The items.
- Storage locations.
- Counting date.
- Responsible personnel.
2. Organize Inventory Movement
The following operations must be controlled:
- Receiving.
- Issuing.
- Transfers.
- Returns.
So that an item is not counted while being moved without recording the movement.
3. Extract the Recorded Balance
The system data to be compared with the physical count is prepared.
4. Physical Counting
The quantities present in storage locations are counted and recorded accurately.
It is preferable to separate:
- Good-condition quantities.
- Damaged items.
- Expired products.
- Reserved products, if the operating method requires this.
5. Compare Physical Quantities with the System
The following can be used:
Inventory difference = Actual quantity - Recorded quantity
If the result is negative → Shortage
If the result is positive → Surplus
6. Investigate the Differences
Do not make the adjustment immediately.
First review:
- The latest sales transactions.
- Purchases.
- Transfers.
- Returns.
- Damaged items.
- Units of measure.
- Data entry errors.
7. Recount Items with Differences
Especially items that are:
- High-value.
- Have large differences.
- Sensitive.
- Fast-moving.
8. Approve the Adjustment
After identifying the cause and obtaining approval from the authorized person, the balance is updated according to the business's accounting and warehouse procedures.
ويدعم نظام DigitalPro for Accounting and Point of Sale monitoring product movement, inventory, warehouses, and suppliers within the same operations system, which helps trace the source of the difference instead of relying only on a final balance.
What Is an Inventory Counting Report?
An inventory counting report is the document that summarizes the result of the inventory counting process and shows the differences between the recorded and actual quantities.
It is preferable for it to include:
| Item | Example |
|---|---|
| Item Code | A-100 |
| Item Name | Product A |
| Warehouse | Main |
| System Balance | 100 |
| Actual Balance | 96 |
| Difference | -4 |
| Unit Cost | SAR 50 |
| Difference Value | SAR -200 |
| Reason | Under Review |
| Action | Recount / Adjustment |
With repeated inventory counting, items that consistently show differences can be analyzed instead of treating each count separately.
Ready to try the system?
Start your free trial or talk to the sales team to help you choose the right solution.
What Causes Inventory Differences?
A difference does not automatically mean theft or loss.
Common causes include:
Receiving Errors
For example, receiving 98 units and recording 100.
Issuing Without Recording
Goods leaving without recording the movement.
Unit of Measure Errors
Such as confusing:
- Piece.
- Carton.
- Package.
Returns
Physically returning the product to the warehouse without updating the system.
Damage and Wastage
Removing the product from use without recording the damage movement.
Transfers Between Warehouses
Deducting the item from one warehouse without completing the receipt in the other.
Counting Errors
Especially with small products or disorganized warehouses.
Barcode or Item Identification Errors
Similar products or duplicate codes may result in recording against another item.
How Can You Reduce Inventory Differences?
Inventory counting alone detects the problem, but it does not prevent it from recurring.
To reduce differences:
- Record every movement when it occurs.
- Use barcodes when appropriate for the business.
- Separate receiving, issuing, and review permissions.
- Organize storage locations.
- Record damaged items immediately.
- Review transfers between warehouses.
- Apply continuous counting to important items.
- Monitor returns.
- Analyze items with recurring differences.
- Link inventory to sales and purchases.
This linkage is one of the key aspects of دليل Warehouse Management، as inventory accuracy is linked to the quality of receiving, issuing, transfer, returns, and damage processes before reaching the adjustment stage.
Manual Inventory Counting or Inventory Counting Using Software?
Inventory counting can be performed manually in small warehouses, but as the number of items and branches increases, managing the process becomes more difficult.
Manual Inventory Counting
It may rely on:
- Count sheets.
- Excel.
- Manual entry of results.
It is suitable for limited operations, but the likelihood of errors increases as the amount of data grows.
Inventory Counting Using an Inventory Management System
It helps with:
- Extracting the recorded balance.
- Managing multiple warehouses.
- Monitoring the movement of each item.
- Recording adjustments.
- Identifying low-quantity products.
- Analyzing inventory differences.
- ربط المخزون بالمبيعات وPurchases.
DigitalPro provides functions for monitoring items, quantities, costs, warehouses, and product movement, in addition to sales, suppliers, and financial and accounting reports.
أما الشركات التي تفضل بيئة تشغيل سحابية، فيعرض cloud accounting system functions for managing inventory, purchases, and item movement within the cloud system.
How Does Inventory Counting Affect Accounting?
Inventory counting is not only a warehouse task, because inventory value affects financial reports, cost of sales, and profitability.
If the system shows more inventory than actually exists, the inventory value used in reports may become inaccurate.
Therefore, it is important to link:
Purchases → Receiving → Inventory → Sales → Cost of Sales → Inventory Counting → Adjustment → Reports
within a single cycle.
يمكنك contact our team to identify the best software suitable for your business or start the free trial to try the system fully.
Common Errors During Inventory Counting
The most common errors include:
- Counting products while issuing continues without control.
- Making an adjustment before identifying the cause of the difference.
- Failing to recount large differences.
- Mixing damaged products with good products.
- Ignoring units of measure.
- Failing to document the person responsible for inventory counting.
- Allowing the same person to count and approve without review.
- Failing to count high-value items frequently.
- Relying only on annual inventory counting in a high-movement warehouse.
- Failing to analyze the causes of differences after inventory counting is completed.
Frequently Asked Questions About Types of Inventory Counting in Warehouses
What are the types of inventory counting in warehouses?
The main types are comprehensive, periodic, continuous or cycle, partial or selective, surprise, and exceptional inventory counting.
What is periodic inventory counting?
It is counting inventory at specified times, such as the end of the month, quarter, or year, and comparing actual quantities with recorded balances.
What is continuous inventory counting?
It is repeatedly counting groups of items throughout the year, along with updating the system for inventory movement with sales, purchases, issues, and transfers.
What is the difference between periodic and continuous inventory counting?
Periodic counting occurs at specified times, while continuous counting relies on repeatedly reviewing groups of inventory throughout the year, allowing differences to be detected early.
What is surprise inventory counting?
It is a counting procedure conducted without prior notice for the purpose of control and verification of the actual balance.
What is partial inventory counting?
It is counting a selected group of products instead of the entire warehouse, such as high-value or fast-moving items.
Does continuous inventory counting eliminate annual inventory counting?
Not necessarily. A business may apply continuous inventory counting throughout the year along with a comprehensive count at a specified time according to its policies and audit requirements.
What should I do when there is an inventory difference?
Recount the item first, then review sales, purchases, returns, transfers, damaged items, and units of measure before approving any adjustment.
Does inventory software prevent inventory differences?
It does not prevent them completely; however, it helps record and track movements and identify the source of the difference more quickly. The quality of procedures, controls, and physical counting remain essential factors.
Conclusion
Understanding the types of inventory counting in warehouses helps a business choose the appropriate control method instead of relying on a single annual count for all situations.
Comprehensive counting provides a complete picture, periodic counting organizes review at specified times, continuous counting helps detect errors early, partial counting focuses on important items, while surprise counting provides an additional control tool.
In many businesses, the solution is to combine more than one type, such as conducting continuous counting for high-value items along with periodic counting for the remaining inventory and comprehensive counting at the end of the period.
Because inventory accuracy begins before the moment of counting, it is important for purchases, sales, transfers, returns, and damaged items to be recorded in one system. You can use Accounting and Point of Sale System to link inventory movement with sales, purchases, suppliers, warehouses, and reports, while the Warehouse Management provides a more comprehensive explanation of the inventory cycle from receiving through counting and adjustment.
Start Managing Your Business with Complete Flexibility
Try Aamal Digital for free. Start issuing your ZATCA-compliant electronic invoices within minutes.
- Free trial without a credit card
- 24-hour technical support
- ZATCA compliant